THE S-CORP ENGINE
A return you can explain.
Bring the source material. Review the facts. Make the tax decisions. PrepReturns connects the work to the return—from conventional Form 1120-S preparation through a finished professional package.
Alpha 14 — human testing and broader operating-business coverage
01 / START WITH THE EVIDENCE
Start where the return starts.
Prior-year returns. Financial statements. Payroll support. Asset schedules. Shareholder history.
These are preparation inputs, not just documents sitting beside a separate data-entry process. Supported source formats produce proposed facts with a connection back to their evidence.
The preparer verifies what the source says, reviews its classification and supplies the judgment a document cannot make.
Follow the preparation path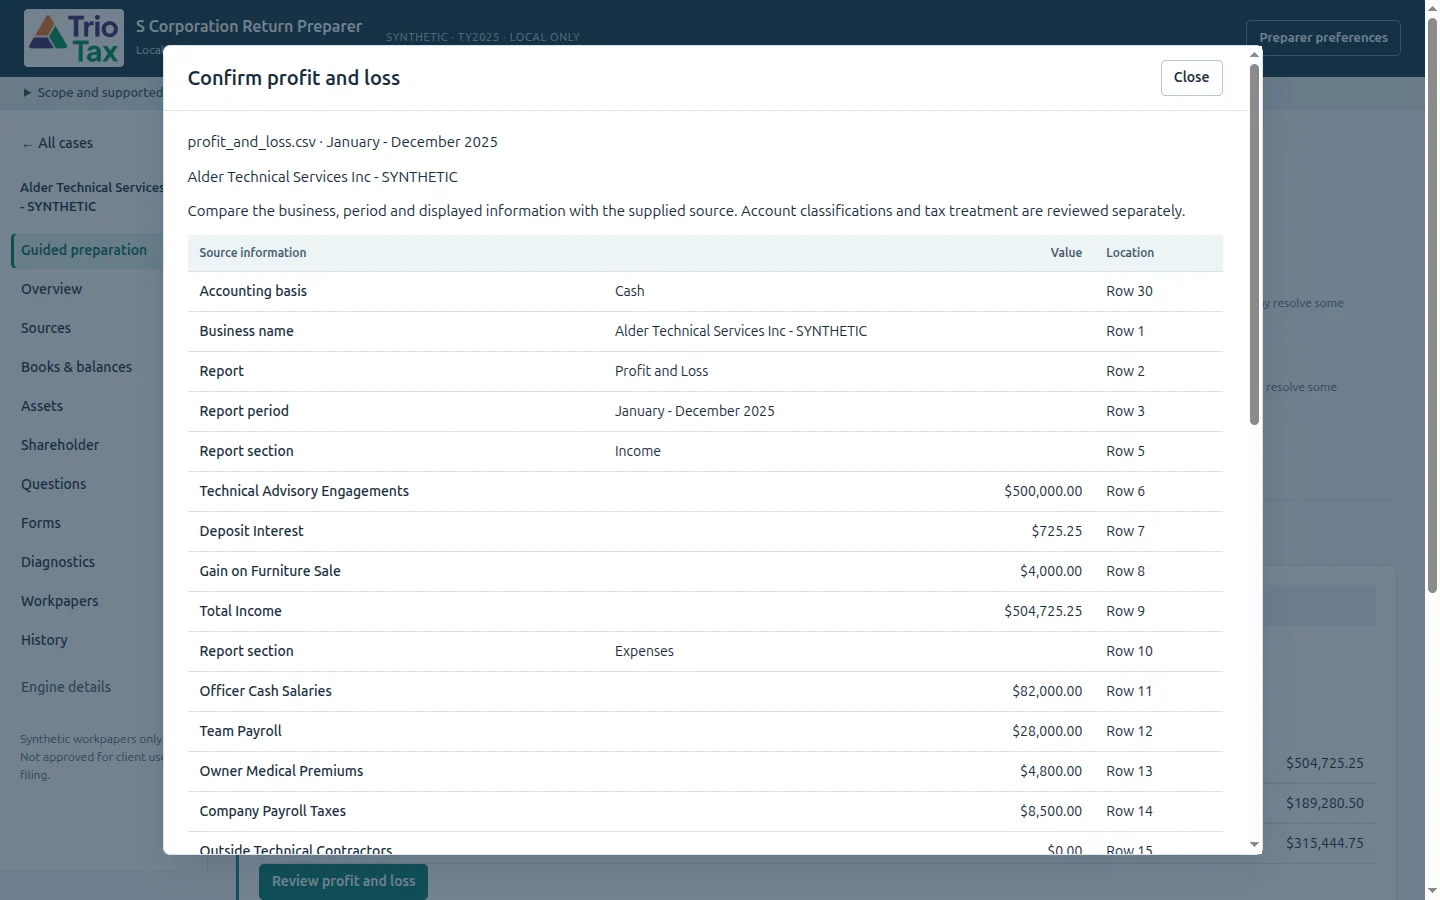
02 / VERIFY THE FACTS
If the document already told us, why type it again?
Extracted and carried-forward facts are proposals. Accept a supported reading, correct a parser error, exclude a duplicate, or establish additional information in the proper workpaper. The source stays original.
A source correction and a tax adjustment do different jobs. One repairs what the software read; the other records the professional treatment of the underlying transaction. Keeping that distinction visible makes the return easier to explain later.
Explore evidence and provenance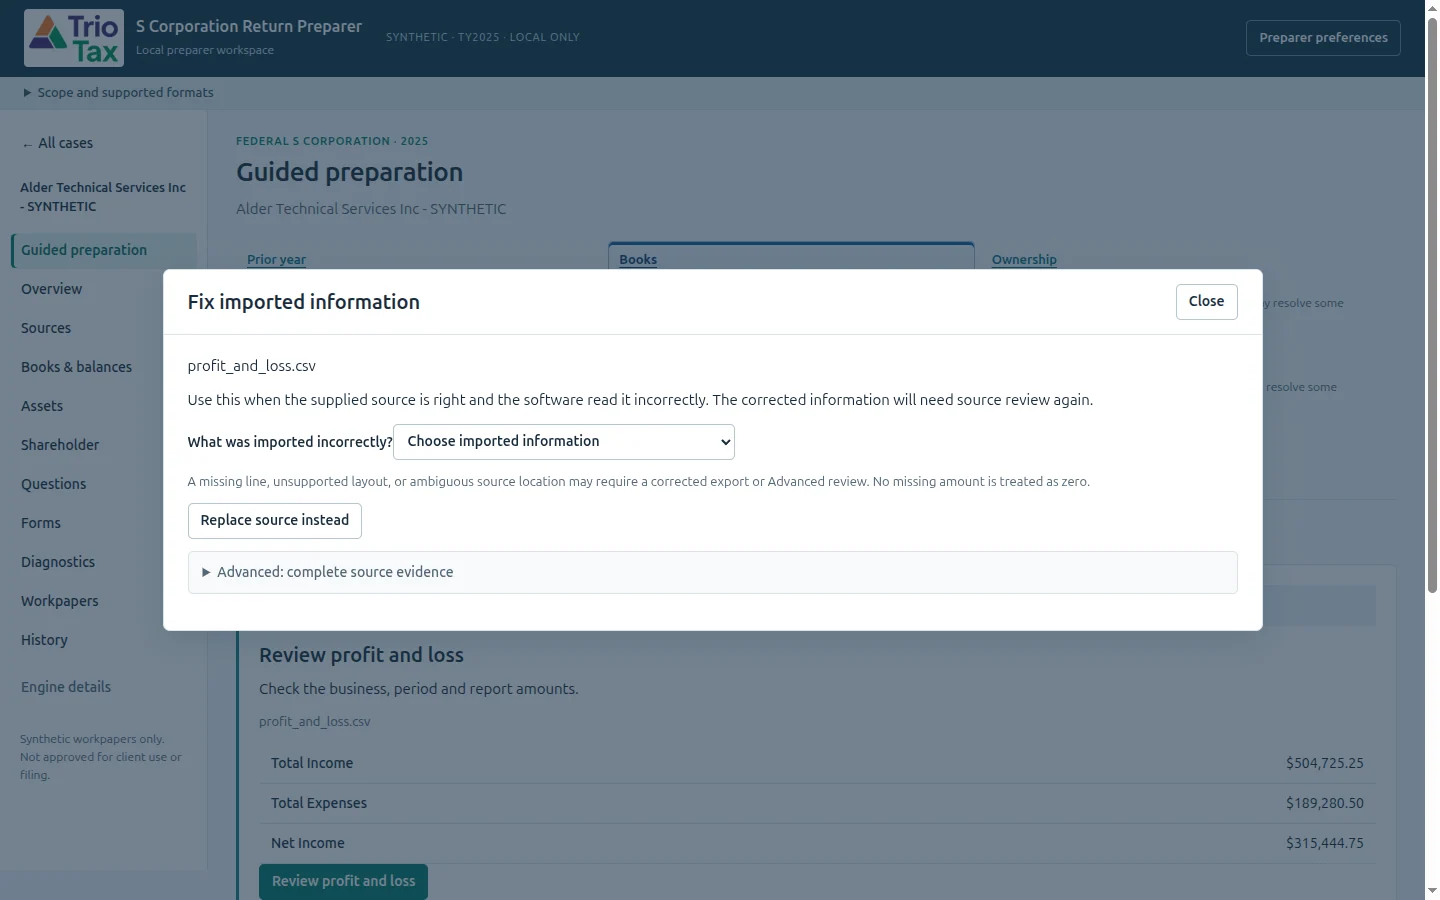
03 / MAKE THE TAX DECISIONS
Ask for what the evidence can’t answer.
Guided Preparation focuses attention on the next useful question: a missing fact, a classification, an election, or a professional decision.
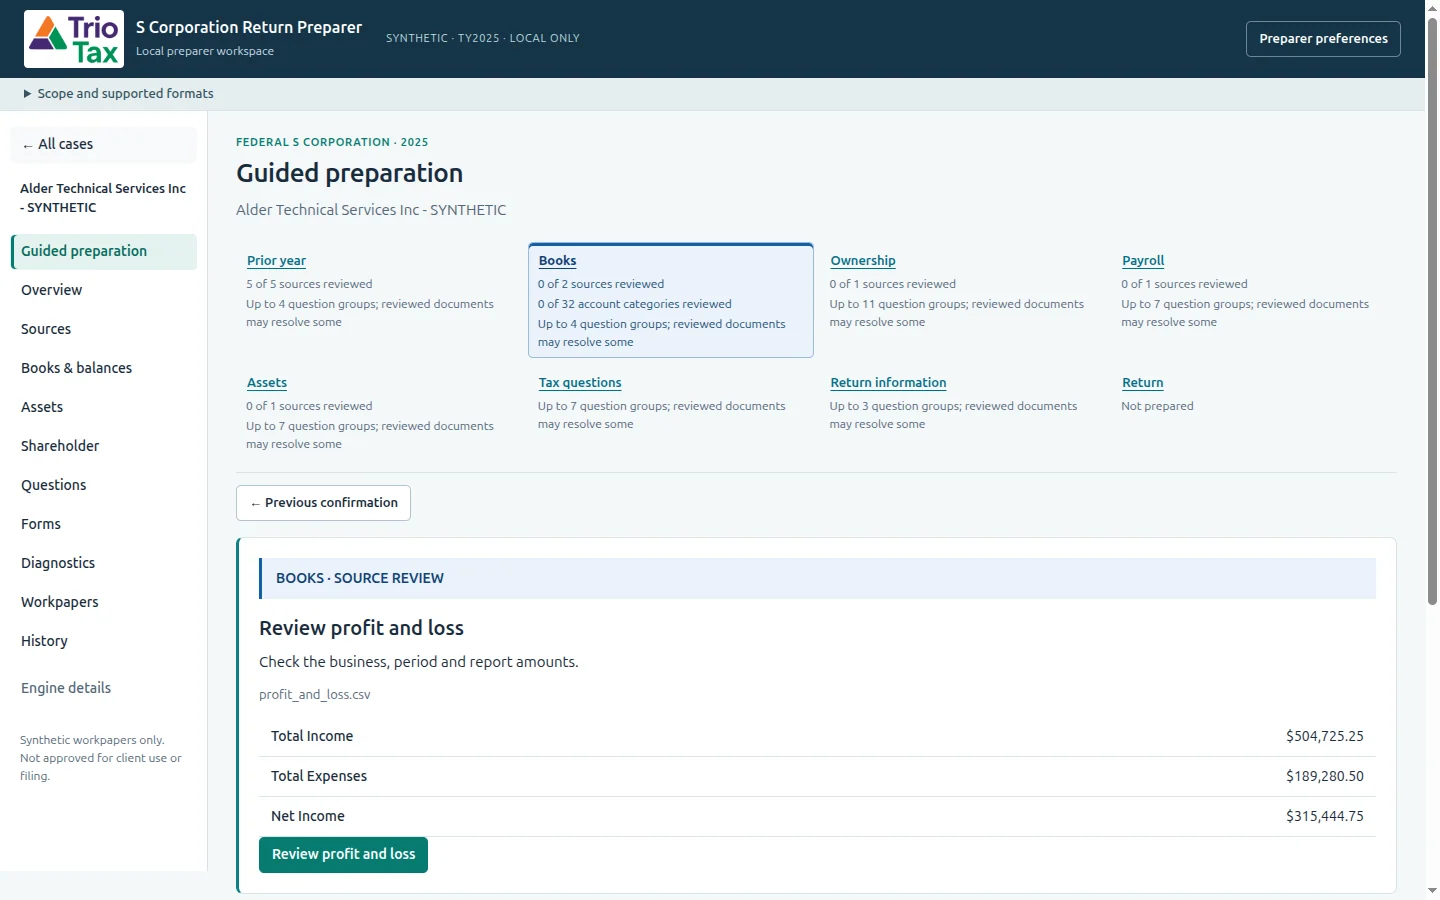
One set of facts.
The guide and direct editors work with the same preparation. Switching views should not mean maintaining a second return.
Unknown stays unknown.
An unresolved opening basis or tax treatment is visible. It is not converted into a convenient zero to keep the workflow moving.
The return stays in view.
Forms, workpapers and “How calculated” explanations give the preparer a direct route from a result back into the work.
A DELIBERATE RETURN UNIVERSE
Capable.
Conventional.
Clearly bounded.
Straightforward does not mean tiny. A business can have real payroll, owners, debt, assets and tax decisions without an exotic underlying structure.
The current engine focuses on federal TY2025 cash-method S corporations in its supported profiles. Each capability has a defined boundary.
What we mean by the straightforward 90%Entity and owners
Conventional federal S-corporation preparation with multiple individual shareholders and owner-specific reporting.
Income and deductions
Ordinary business income, deductions, book-to-tax adjustments, paid shareholder-loan interest and accountable-plan reimbursements.
Assets, vehicles and amortization
Depreciation, supported section 179 and bonus/MACRS, dispositions, listed property, and startup, organizational and intangible amortization.
Official forms and corporate reporting
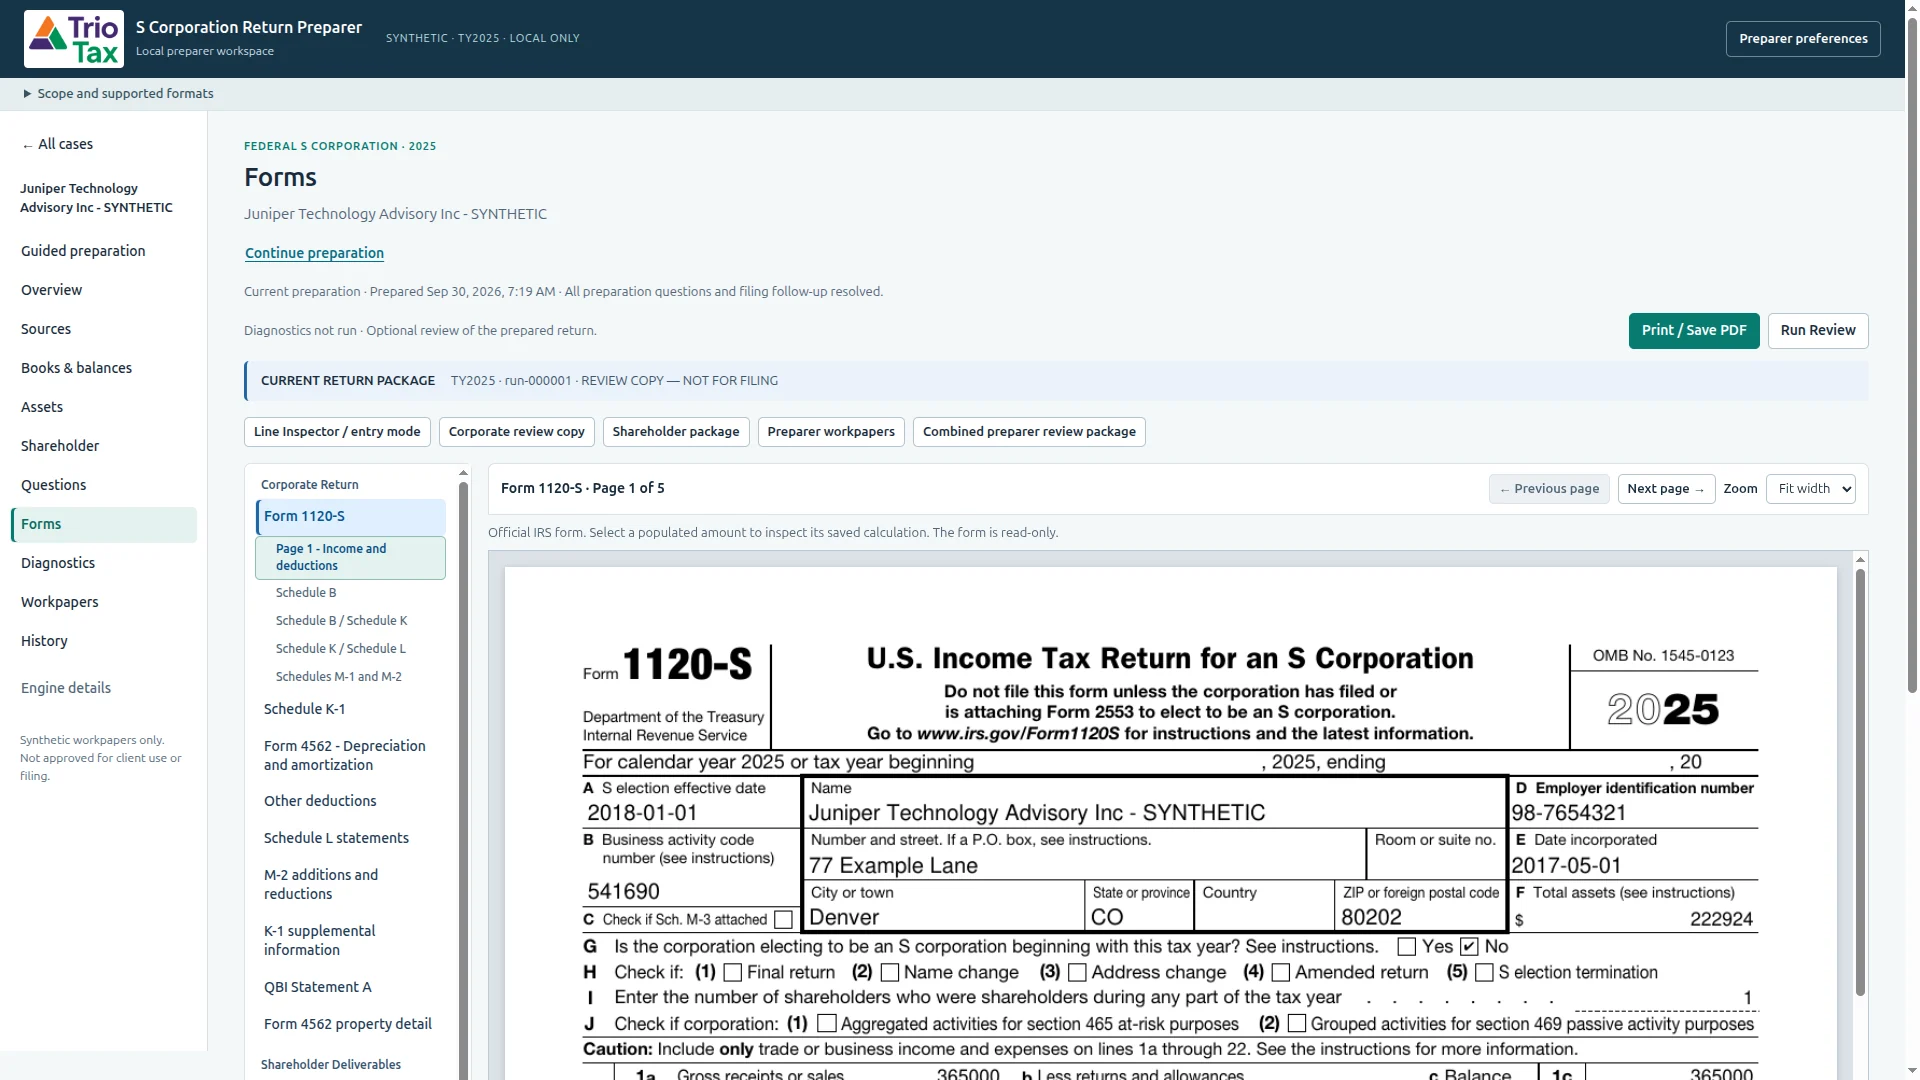
Actual Form 1120-S, K-1, applicable supporting forms, book-to-tax schedules and corporate QBI information.
Review, history and output
Source review, Guided Preparation, workpapers, How calculated, optional diagnostics and saved professional return packages.
MEET CEDARLINE · SYNTHETIC EXAMPLE
An ordinary business can have a lot going on.
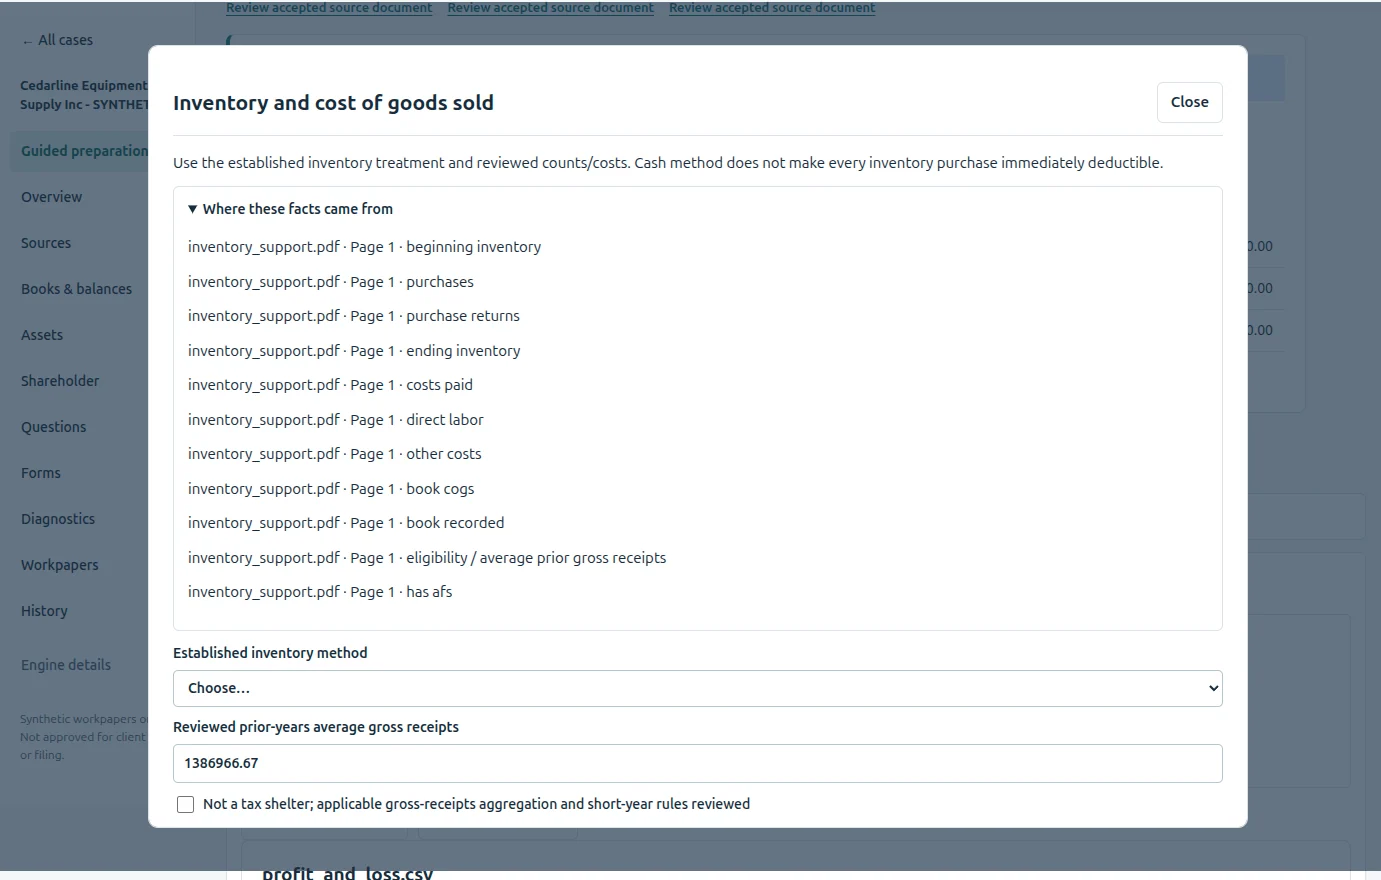
Cedarline Equipment & Supply brings the broader Alpha 14 capabilities together: two shareholders, inventory, a commercial rental, brokerage sales, a company car, amortization, paid shareholder-loan interest and accountable-plan reimbursements.
Each area still needs its own facts and treatment. Inventory does not become an ordinary expense by accident. Rental income keeps its character. A payment already in the books does not get posted again.
That is the point of a richer synthetic example: test the connections, not just the isolated feature.
04 / REVIEW AND PRODUCE
The output is the tax return.
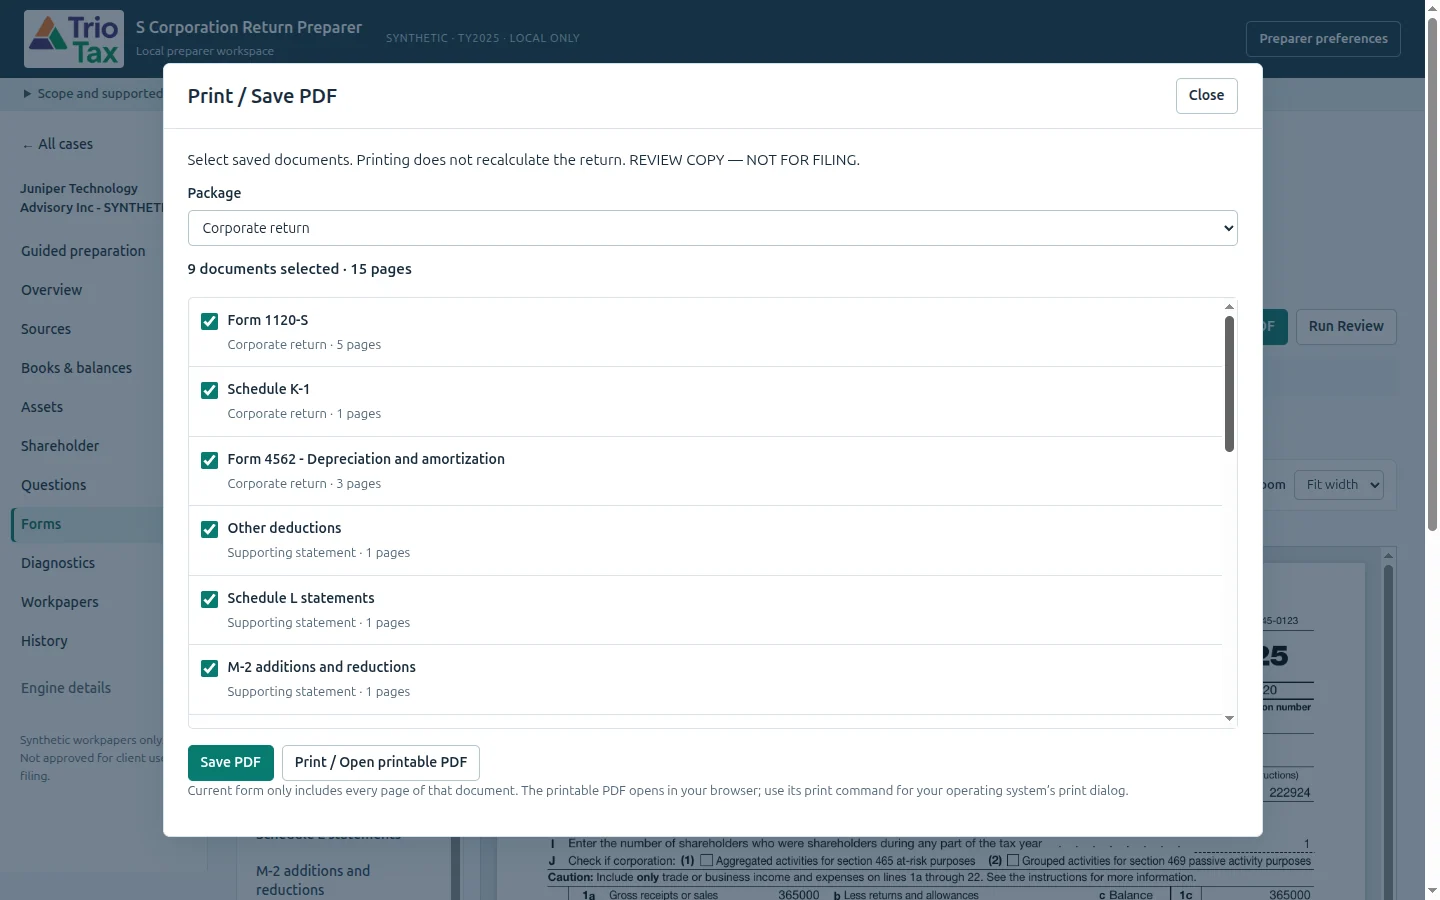
Actual IRS forms. Shareholder packages. Supporting statements. Professional workpapers. All connected to the saved preparation.
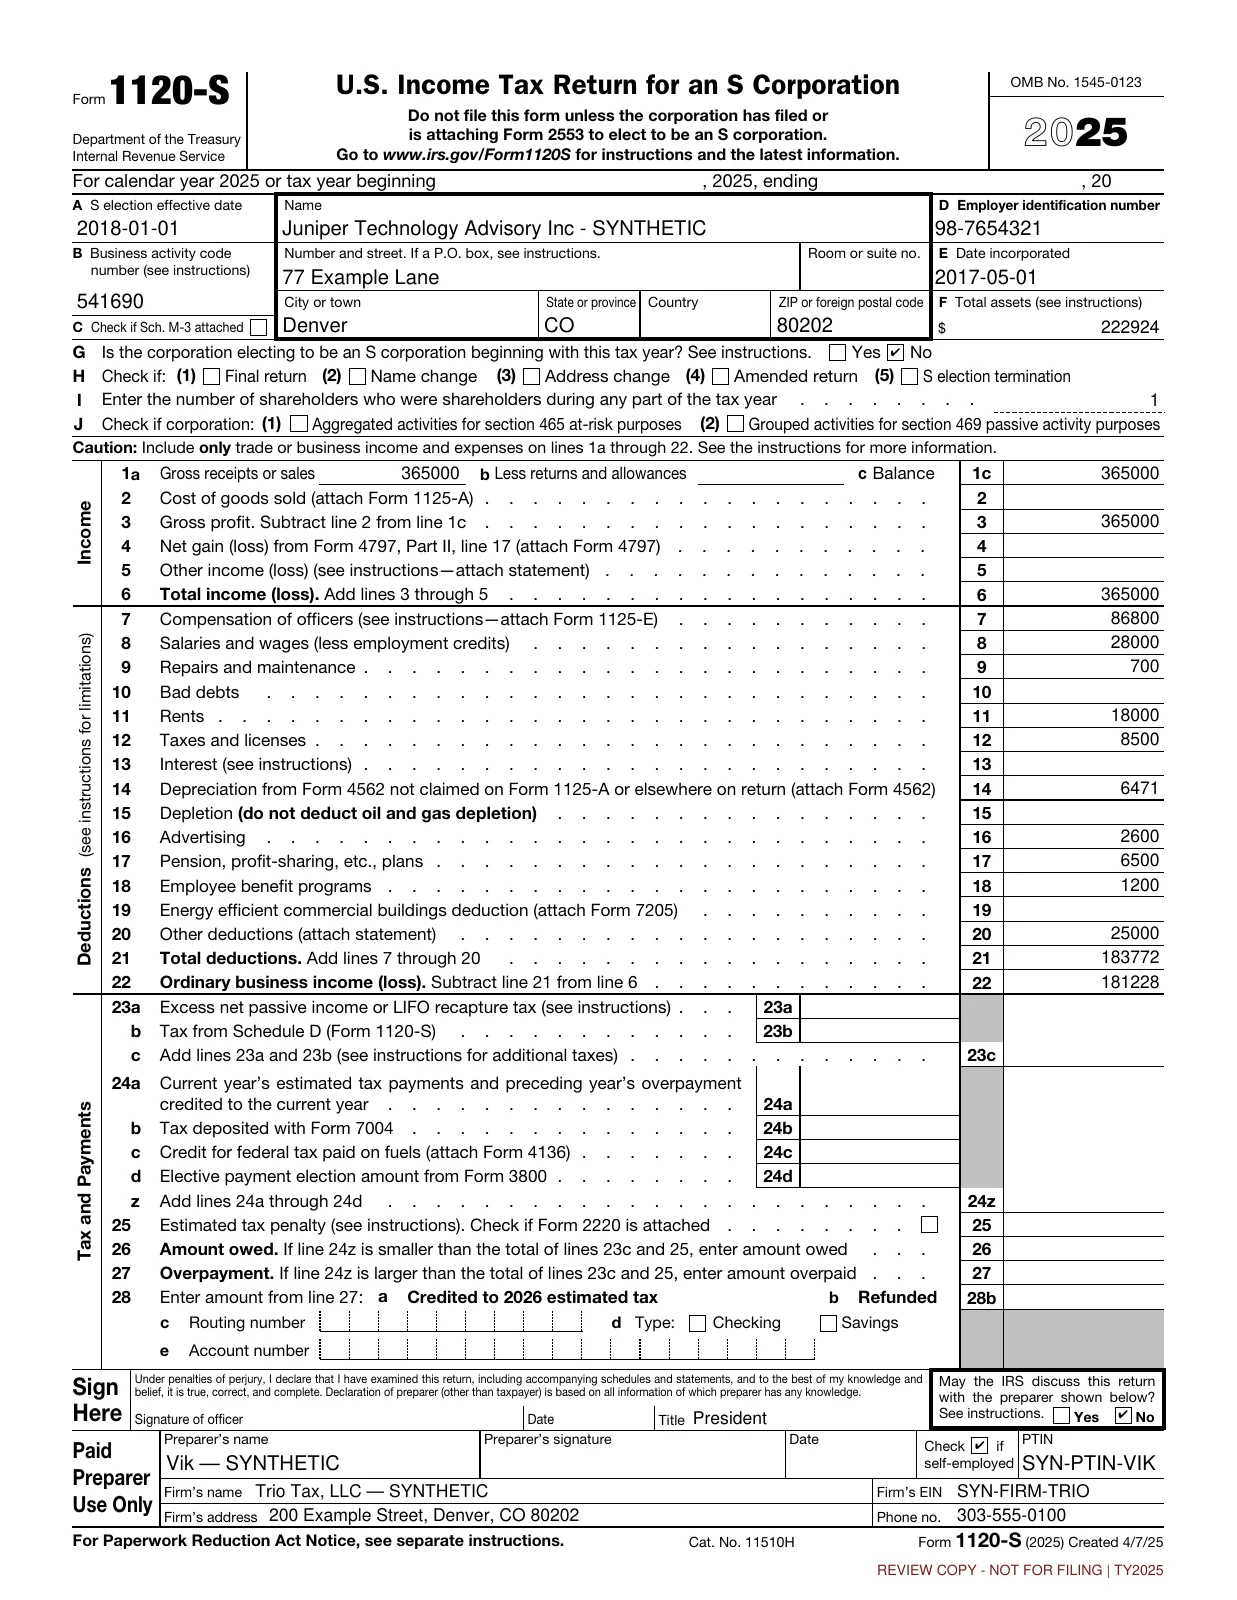
A package with an internal logic.
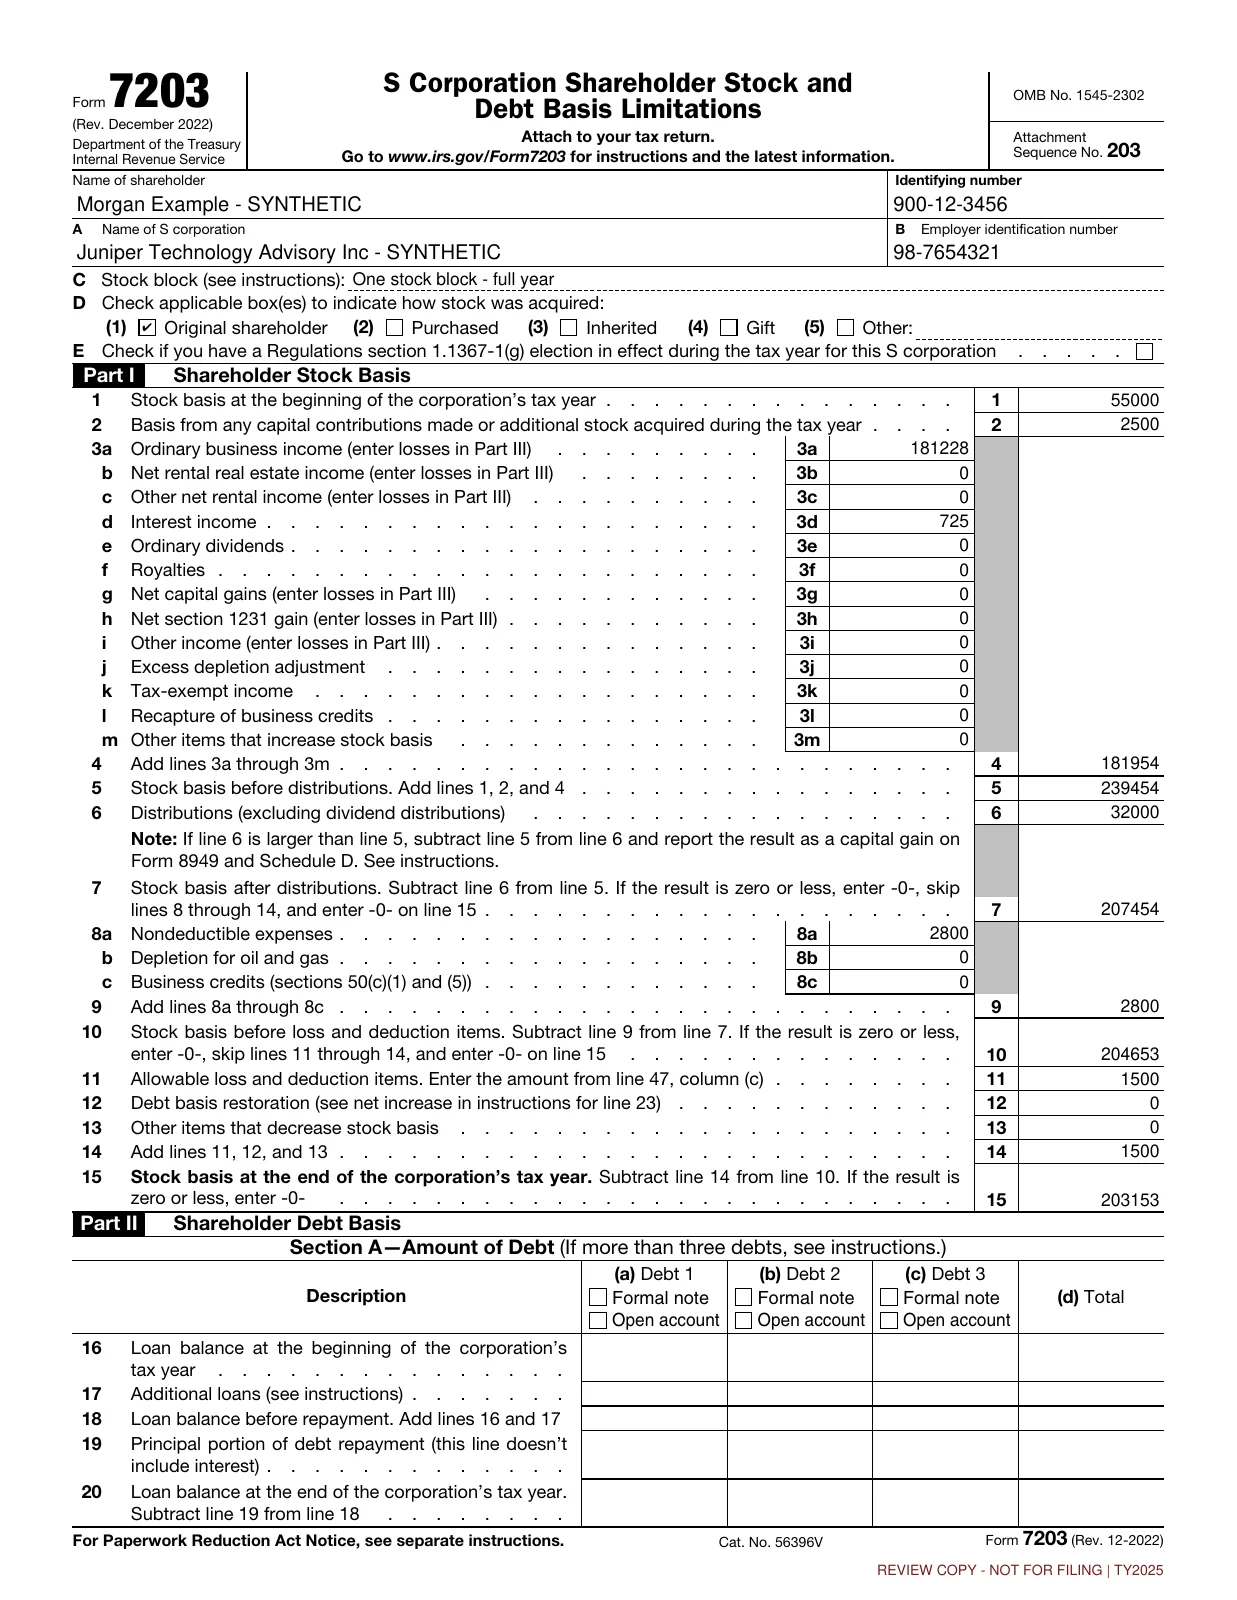
The corporate return, shareholder deliverables and internal workpapers have distinct places in the package. Each supported shareholder receives the applicable K-1, basis information and Form 7203 output.
Forms, explanations and diagnostics refer to the same saved result. Print / Save PDF selects from that result; it does not recalculate a different return.
History remains history.
Change an input and the current package becomes stale. Update Return creates a new preparation. The earlier package remains tied to the evidence and facts that produced it.
Here, “finished return” describes preparation and output. The public project does not provide e-filing, transmission, signatures or IRS approval. The examples shown are synthetic review copies.
Read the product boundariesThe corporation reports.
Each K-1 carries the owner’s corporate allocation. Basis limits do not silently reduce what the corporation reports.
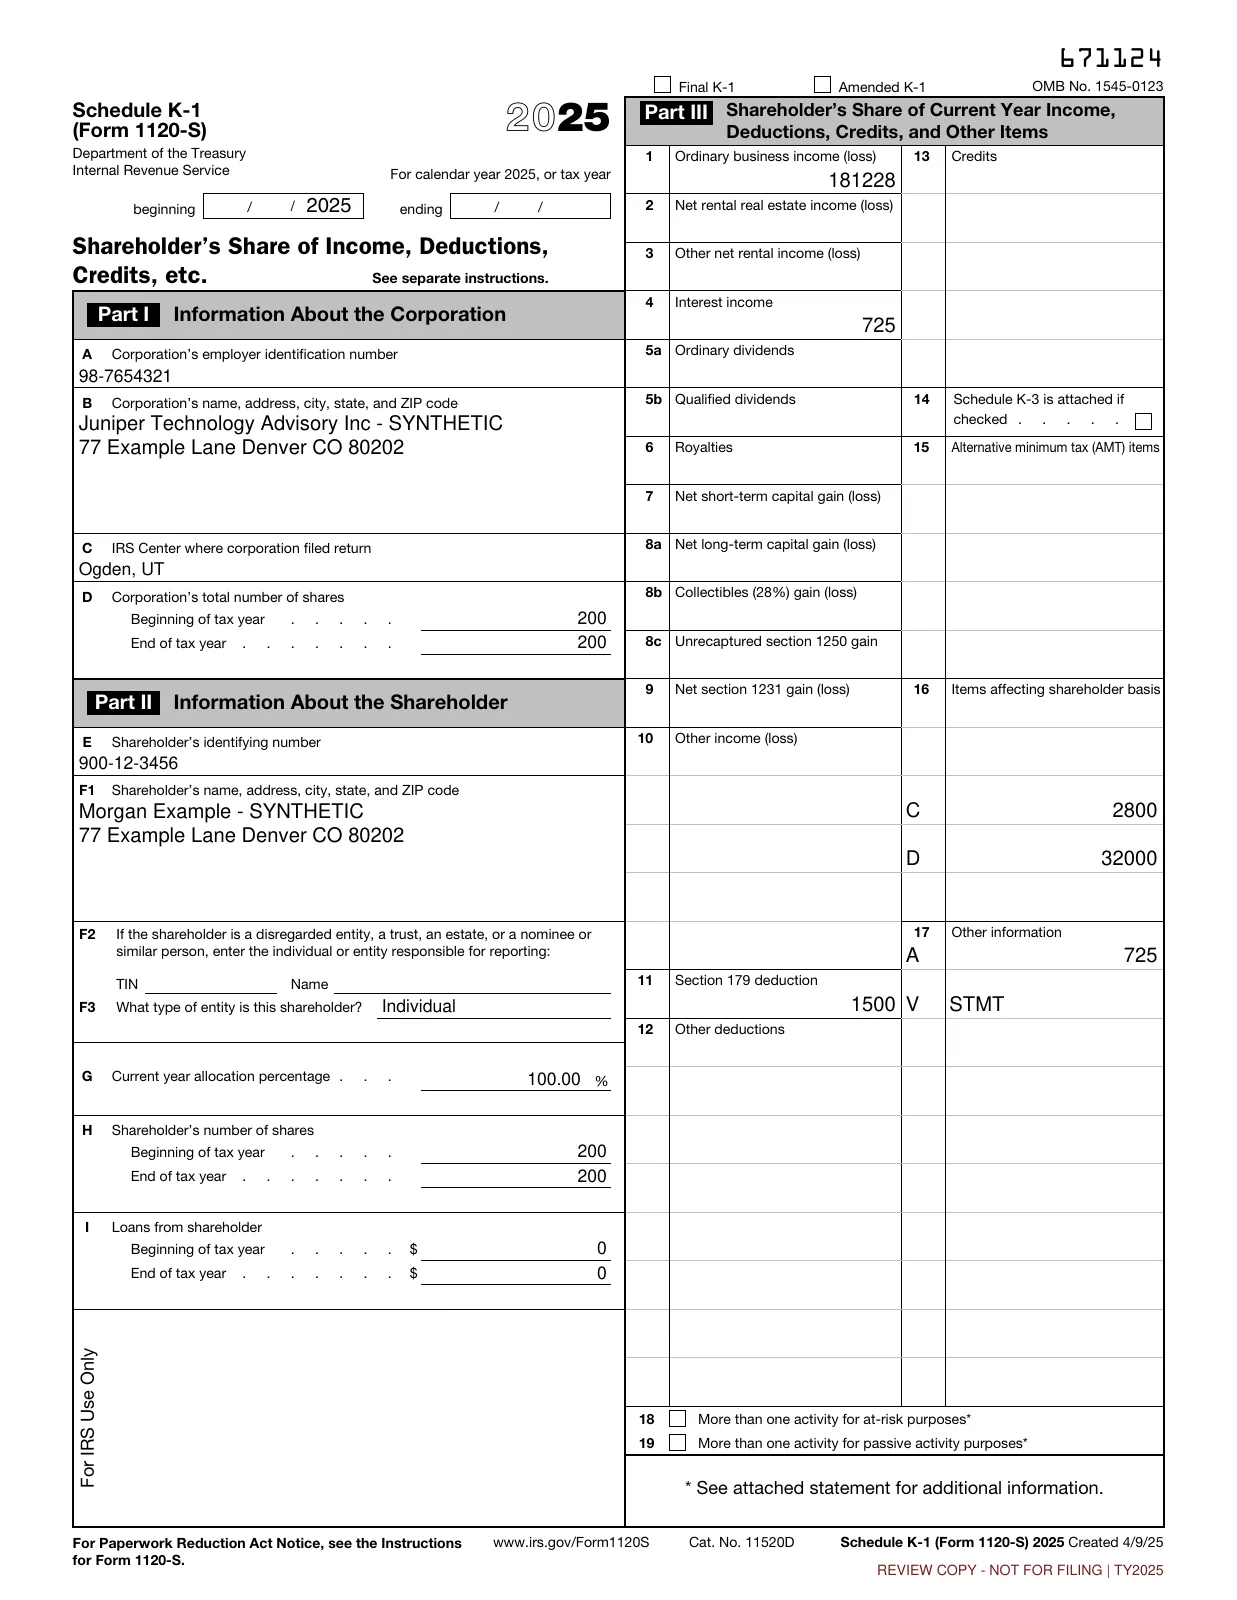
Follow the work behind the return.
Successive Alphas connected source evidence, professional decisions, calculations and visible output. The hard parts are worth seeing.